

By Olusegun Obisanya
Consolidated Hallmark Insurance Limited has secured an upgraded A+(NG) financial strength rating from GCR Ratings after sharply improving its underwriting performance and strengthening its capital and liquidity position.
The rating agency, in an assessment announced on August 31, 2026, upgraded the insurer from A(NG), previously on a Stable Outlook, to A+(NG) with a Positive Outlook.
In a release signed by the Head, Brand and Communications, Consolidated Hallmark Insurance Plc, Ajibola Liyide, stated that the upgrade followed a sharp reduction in the company’s combined ratio from 113.5 per cent in 2023 to 83.9 per cent in 2024 and 78.2 per cent in 2025, significantly outperforming the 95 per cent average for Nigeria’s non-life insurance industry.
GCR said the improvement was driven by fewer high-value claims, optimised reinsurance arrangements, scale efficiencies and disciplined cost management.
The upgrade represents the first improvement in GCR’s rating of the insurer since it commenced coverage in August 2023.
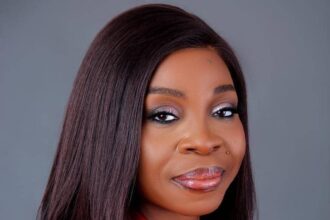
The Managing Director/Chief Executive Officer of Consolidated Hallmark Insurance, Mrs Mary Adeyanju, said the rating validated the company’s focus on underwriting discipline and financial resilience.
She said, “The A+(NG) rating is a strong affirmation of the discipline and resilience behind our transformation. We have deliberately strengthened underwriting quality, risk management and reinsurance while ensuring that our growth remains supported by adequate capital and liquidity.
“Most importantly, this milestone reinforces the confidence of our customers, brokers and partners in our ability to deliver on our promises.”
The insurer recorded a 33.7 per cent five-year compound annual growth in insurance revenue, reaching N41.7bn in 2025, supported by its distribution network and intermediary relationships across eight business lines.
Its capital adequacy ratio rose to 2.5x from 1.9x, while its statutory solvency margin stood at 11.9x, against the regulatory minimum of 1.0x. Liquidity coverage remained strong at 2.2x, with cash and short-term placements accounting for 54.8 per cent of investments.
Adeyanju said the positive outlook would push the company to maintain its focus on sustainable growth.
“Our objective is not growth for its own sake. We are focused on profitable, sustainable and responsible growth. The Positive Outlook is encouraging, but it also raises the standard we have set for ourselves,” she posited.
She added that the company would continue investing in underwriting excellence, innovation, customer experience, operational efficiency and prudent capital management.
GCR said further rating improvement would depend on sustained underwriting and competitive gains while maintaining adequate capitalisation and liquidity.
It projected the company’s capital adequacy ratio to remain between 2.2x and 2.4x and liquidity coverage above 2.0x over the next 12 to 18 months.