

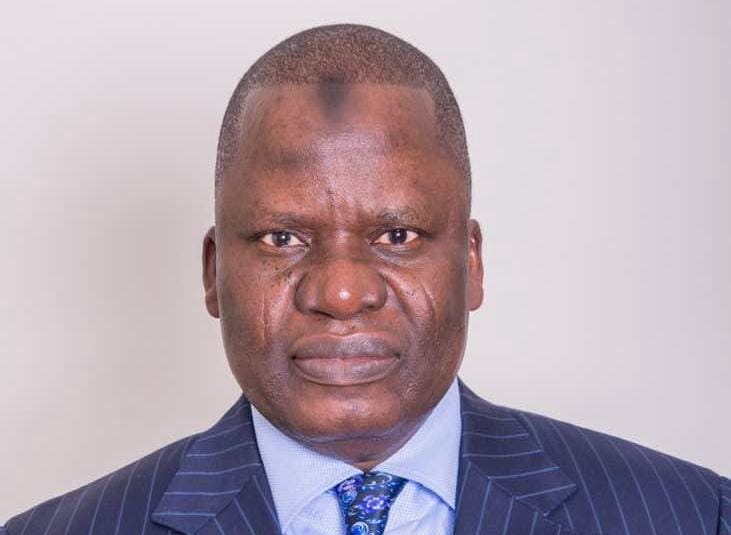
By Suleyman A. Ndanusa, PhD, OON
Something unusual and potentially important has happened in Abuja. The Federal Ministry of Finance and the Central Bank of Nigeria have signed a Memorandum of Understanding to coordinate fiscal and monetary policy.
On the surface, this sounds like an agreement between two institutions that should have been coordinating all along. It is a little like a husband and wife issuing a joint communiqué announcing that they have agreed to discuss the household budget. One is pleased that peace has broken out, but slightly curious about how the house was previously being run.
Yet the MoU deserves serious attention. The Ministry and the CBN are the two most powerful hands on Nigeria’s economic steering wheel. One taxes, spends and borrows. The other manages money, interest rates, banking liquidity and foreign exchange. Their mandates are different, but their consequences meet every day in the price of food, the cost of credit, the value of the naira, the government’s debt service bill and the ability of businesses to survive.
When these two institutions work at cross purposes, the economy behaves like a car in which one foot is pressing the accelerator while another is pressing the brake. The engine makes an impressive noise, fuel disappears rapidly, the passengers become anxious, and remarkably little distance is covered.
The new MoU is intended to improve information sharing, align macroeconomic assumptions and forecasts, coordinate government cash management and debt issuance, strengthen liquidity forecasting and provide mechanisms for addressing conflicting policy actions. It also places the pursuit of sustainably lower inflation at the centre of the relationship.
These are sensible objectives. But the more important question is not whether coordination is desirable. It is whether this particular agreement can become part of a wider system that aligns policy across the Nigerian economy.
Some months ago, I advanced the argument that Nigeria’s central economic difficulty is not a policy deficit but a coordination deficit. We are rarely short of policies, plans, committees, agencies or declarations. What is frequently missing is the capacity to make them reinforce one another.
A government may announce an agricultural programme while insecurity keeps farmers away from their land. The CBN may tighten monetary policy to control inflation while government borrowing injects more liquidity and pushes up interest rates. Trade policy may encourage domestic production while customs arrangements delay essential industrial inputs. Government may seek foreign investment while regulatory uncertainty quietly escorts investors to the airport.
Every policy may appear defensible when examined alone. The problem becomes visible when they are placed together.
That is why coordination and policy alignment are related but not identical. Coordination improves communication among institutions. Policy alignment ensures that their decisions, resources, incentives and timelines reinforce a common national outcome. Coordination may get everyone into the meeting room; alignment ensures they are discussing the same problem and travelling in the same direction.
The Finance and CBN MoU is therefore best understood as a potentially important building block within a Nigerian Policy Alignment Framework. It is not yet the framework itself.
Our earlier work identified five dimensions of alignment, strategic, institutional, fiscal, delivery and outcome alignment. Tested against those dimensions, the MoU makes a promising beginning, but it also reveals the distance still to be travelled.
At the strategic level, the agreement appears to establish lower inflation, macroeconomic stability and stronger economic growth as common objectives. That is useful, but these broad aspirations must be translated into a shared economic story. What inflation path is Nigeria pursuing? Over what period? What rate of growth is required to raise income per person? What combination of public borrowing, private credit, exchange rate stability and investment is consistent with those objectives?
Without agreed answers, the Ministry may celebrate increased expenditure, the DMO may celebrate successful borrowing, the CBN may celebrate reduced liquidity, and the citizen may wonder why the combined celebration has not reduced the cost of living.
Institutional alignment requires clarity about roles. The Ministry manages fiscal policy. The CBN maintains monetary and price stability. The Debt Management Office manages public debt. The Budget Office prepares and monitors the budget. The National Bureau of Statistics supplies the evidence on which the entire enterprise depends. Revenue agencies collect the funds, while sector ministries and state governments deliver much of what eventually determines prices and production.
The MoU connects two important institutions, but Nigeria’s policy ecosystem contains many more moving parts. Inflation does not report exclusively to the Finance Ministry or the CBN. Food inflation has an agricultural address. Transport costs have an infrastructure and energy address. Imported inflation has an exchange rate and trade address. Insecurity has a national security address. Electricity costs have a power sector address. Nigeria cannot defeat a many parented problem through a two member family meeting.
Fiscal alignment is where the MoU may make its most immediate contribution. Government borrowing, cash releases and debt service payments have powerful effects on banking liquidity and interest rates. If the Ministry releases large sums unexpectedly, the CBN may have to mop up the resulting liquidity. If government borrows heavily from the domestic market, banks may prefer the comfort of government securities to the adventure of lending to manufacturers and farmers.
The government then complains that businesses cannot obtain affordable credit, while the CBN tightens policy to restrain inflation and protect the currency. Everybody is busy, everybody has an explanation, and the entrepreneur is still waiting for a loan.
A credible framework should align the federal budget, borrowing programme, government cash plan and monetary policy calendar. The Ministry, DMO and CBN should know in advance when major revenues, FAAC distributions, debt maturities, bond auctions and capital releases will affect liquidity. Predictability would reduce unnecessary monetary interventions, moderate financing costs and give financial markets a clearer view of government’s requirements.
Delivery alignment asks a more practical question: who does what on Monday morning?
This is where many Nigerian agreements become less talkative. They contain admirable objectives but avoid assigning responsibilities, timelines, indicators and consequences. Once the signing photographs have circulated, the agreement begins a peaceful retirement in somebody’s filing cabinet.
The MoU needs an implementation compact specifying who convenes, who supplies which data, who resolves differences, who monitors performance and what happens when agreed actions are delayed. There should be a small professional secretariat, preferably built around existing institutions rather than another large bureaucracy. Nigeria needs better coordination, not another agency requiring a headquarters, official vehicles and a launch ceremony.
Outcome alignment is the final and most important test. The success of this agreement cannot be judged by the number of meetings held or communiqués released. It must be measured by what changes in the economy.
Does inflation decline sustainably? Does government borrowing become more predictable and less expensive? Does private sector credit increase? Do manufacturers obtain finance on more reasonable terms? Does exchange rate volatility moderate? Are reserves strengthened through durable export and investment flows? Do growth, productivity, employment and household purchasing power improve?
Macroeconomic indicators are not decorative trophies. Their purpose is to improve the conditions under which citizens and businesses live and invest.
Other countries provide useful lessons, although no foreign arrangement can simply be photocopied and pasted onto Nigeria.
The United Kingdom offers one of the clearest examples of coordination with defined boundaries. The government sets the inflation target, but the Bank of England has operational independence to pursue it. The Debt Management Office was created in 1998 to separate government debt management from monetary policy. Borrowing calendars are published, the Treasury and the Bank exchange information, and institutional responsibilities are visible.
The result is not that Britain has abolished inflation or economic mistakes. Recent history would quickly correct anyone making such a heroic claim. The achievement is that the system tells the public who is responsible for what. When inflation departs materially from target, the Governor must explain the deviation and the proposed response. Coordination has not eliminated accountability; it has made accountability easier to locate.
The lesson for Nigeria is straightforward. Government and the CBN may agree on national objectives and share information, but the MPC must retain operational control over monetary policy. Coordination must not become a respectable name for political pressure on interest rates or exchange rate decisions.
New Zealand provides an equally important lesson. It pioneered modern inflation targeting by combining a clearly defined price stability objective with central bank operational independence. At the same time, its fiscal responsibility framework requires transparent economic forecasts, disclosure of fiscal risks and regular reporting on the government’s financial position.
The central bank is not expected to guess what fiscal policy is doing, and the government cannot easily disguise the future consequences of today’s decisions. Fiscal and monetary authorities may hold different views, but they work from a transparent body of evidence.
For Nigeria, the lesson is that coordination without fiscal transparency will remain incomplete. The MoU should be supported by published medium term fiscal projections, credible cash flow forecasts, disclosure of contingent liabilities and transparent limits on central bank financing of government.
South Africa offers a nearer African comparison. Its constitution protects the independence of the South African Reserve Bank while requiring regular consultation with the minister responsible for finance. The National Treasury operates a medium term expenditure framework, and the Reserve Bank publicly explains its inflation targeting decisions.
That system has helped preserve a degree of macroeconomic credibility through difficult political and economic periods. But South Africa also demonstrates the limitations of fiscal monetary coordination. Sound meetings between the Treasury and central bank cannot generate electricity, repair ports or solve structural unemployment. Macroeconomic coordination can create stability; it cannot substitute for effective sector policies and delivery institutions.
This point is particularly relevant to Nigeria. The CBN cannot raise agricultural output with the Monetary Policy Rate. The Ministry of Finance cannot secure farms through a budget circular. Fiscal and monetary alignment must therefore connect with agriculture, energy, transport, trade, security and state level delivery.
Indonesia adds a further institutional lesson. It created a Financial System Stability Committee bringing together the Ministry of Finance, Bank Indonesia, the financial services regulator and the deposit insurance authority. The committee provides a structured platform for surveillance, information sharing and crisis management while preserving the statutory responsibilities of the participating bodies.
During the COVID-19 emergency, Indonesia also experimented with extraordinary central bank support for government financing. The arrangement helped manage an exceptional crisis, but it was explicitly treated as exceptional and time bound because permanent monetary financing could undermine central bank credibility.
Nigeria should absorb both sides of that lesson. A standing coordination platform is valuable, particularly during crises. But extraordinary cooperation must not become ordinary fiscal dependence.
There are also cautionary examples. Ghana’s recent experience showed how quickly fiscal stress, heavy borrowing and central bank financing can weaken the currency, accelerate inflation and eventually require painful debt restructuring. Coordination is not inherently virtuous. If it is used to make the central bank accommodate fiscal excess, it becomes fiscal dominance conducted by committee.
The best international systems therefore share certain qualities. They establish common objectives, protect institutional mandates, publish credible data, coordinate debt and cash management, define crisis procedures and make officials explain deviations. They coordinate actions without erasing responsibility.
This is where Nigeria’s new MoU should now lead.
The Finance Ministry and CBN should develop an Outcome Delivery Compact around a small number of measurable national objectives: sustainable disinflation, fiscal stability, exchange rate resilience, affordable productive credit and stronger private investment. The compact should identify the policy drivers of each outcome, assign institutional responsibilities and establish clear escalation procedures when one institution’s actions threaten the shared objective.
A permanent technical platform should connect the Ministry and CBN with the DMO, Budget Office, Accountant-General, NBS and revenue agencies. Sector institutions should participate when the issues involve food, energy, trade, infrastructure or security. States should be included where implementation depends on them.
This should operate as a coordination wheel rather than a new super ministry. The Minister of Finance and Coordinating Minister of the Economy should orchestrate the economic policy ecosystem, but orchestration is not the same as command. The conductor aligns the performance; he does not seize every instrument from its player.
The arrangement also needs a Real Time Fiscal and Monetary Coordination Dashboard. It should track revenue, expenditure, government cash positions, debt issuance, banking liquidity, inflation and food prices, foreign exchange flows, reserves, private sector credit and major supply bottlenecks. It should provide early warning when fiscal operations are likely to undermine monetary objectives or when monetary tightening is imposing unsustainable costs on government finance and productive activity.
The dashboard should not become another colourful screen admired during official visits. It must support decisions, assign responsibility and record whether corrective actions were taken.
Quarterly policy alignment reviews should examine not only what each institution has delivered but whether those deliveries combine into the intended result. A successful bond auction may satisfy the DMO, but if it severely crowds out private credit, the wider outcome may be less satisfactory. A high interest rate may reduce liquidity, but if food inflation is being driven mainly by insecurity and transportation costs, monetary restraint alone may impose considerable pain for limited gain.
This is the difference between institutional performance and national outcomes. Government should not merely ask, “Did every agency perform its assigned task?” It should also ask, “Did all those tasks add up to the result Nigerians were promised?”
Public accountability must complete the framework. The authorities should publish the MoU or a detailed implementation summary, state the inflation objective and time horizon, disclose fiscal risks and issue periodic reports on agreed indicators. Any use of Ways and Means financing should remain within the law, be transparently reported and carry enforceable repayment arrangements.
The central bank must retain the ability to say no. An institution that cannot say no to government cannot credibly promise price stability to the public.
The MoU is therefore encouraging, but it should be treated as the beginning of alignment rather than its completion. It connects the country’s two principal macroeconomic institutions, but the wider ecosystem must still be joined. Strategy must connect to policy; policy must connect to institutions; institutions must connect to resources and timelines; delivery must connect to measurable national outcomes.
Nigeria has had many good policies. Some have failed not because the ideas were wrong, but because surrounding policies were moving in different directions. Implementation failure is often the symptom; coordination failure is frequently the disease.
The new agreement provides an opportunity to treat that disease. It can establish a common evidence base, improve borrowing and cash management, support credible inflation targeting and create early warning against policy contradictions. More importantly, it can become the first practical building block of an integrated national policy alignment system.
But the distinction between a signed document and a functioning system must remain clear. An orchestra does not become harmonious merely because the musicians have exchanged telephone numbers. They require a common score, defined roles, disciplined timing, an effective conductor and an audience capable of deciding whether the performance was worth the ticket.
Nigeria now has the beginnings of that common score. The task is to expand the duet between Finance and the CBN into an orchestra of aligned economic institutions without allowing anyone to confiscate the CBN’s instrument.
Good policies create possibilities. Effective policy alignment creates results. Nigerians have waited long enough for the results.
Suleyman A. Ndanusa, PhD, OON, is an economist, lawyer, strategic studies scholar, and public policy thinker and practitioner with extensive experience in financial markets, regulation, governance, national Security and development.